Overview
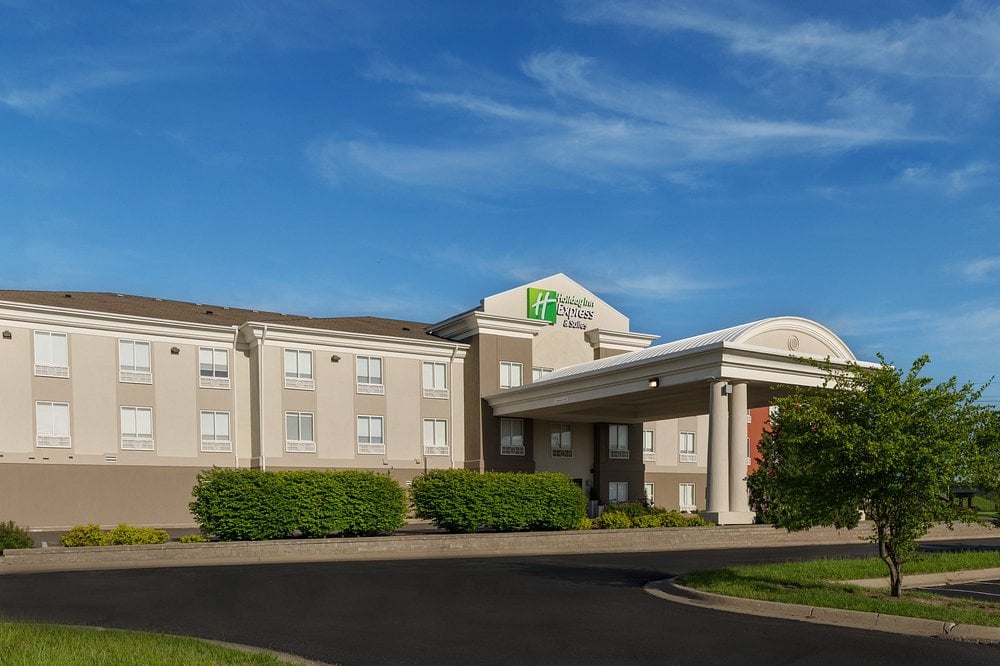
HREC Investment Advisors is pleased to offer, to qualified investors, the opportunity to acquire the fee simple interest in the 78-room Holiday Inn Express & Suites Lawrence (“Hotel” or “Property”), situated at 3411 S Iowa St, Lawrence, KS 66046. The Hotel opened in 2001 and is located a short distance away from the University of Kansas.
The acquisition of the Holiday Inn Express & Suites Lawrence offers a rare opportunity to acquire a well-located asset a short distance from the University of Kansas, a Big 12 university. The University of Kansas enrolls more than 25,000 students at its Lawrence campus, and the Kansas Jayhawks compete at the highest level in the NCAA. Allen Fieldhouse, located on the university's campus, is one of the most prestigious college basketball venues in the country, and the Jayhawks have sold out nearly 400 consecutive men's basketball home games dating back to the 2001-02 season.
The University of Kansas (KU) has reshaped Lawrence's corporate landscape, with biosciences and advanced manufacturing becoming more prominent than ever. Since 2010, more than 30 companies have established offices in or near Lawrence to capitalize on their partnership with KU, with many locating within the KU Innovation Park or Lawrence VenturePark. Additionally, 25 percent of the university's out-of-state students stay in Kansas after graduation, making the university the leading talent magnet in the state.
The Hotel presents a compelling opportunity for a new owner to capture continued upside. TTM RevPAR through May 2026 is up 9.1% year-over-year, pushing RevPAR penetration to nearly 120% — demonstrating clear, sustained cash flow momentum. The Property will also be sold unencumbered by brand, as the current franchise agreement expires February 1, 2027 and will not be renewed, giving a buyer maximum flexibility to pursue a conversion. With limited new supply in the pipeline, a new owner is well positioned to acquire a well-located, cash-flowing asset in a Big 12 market.
Investment Highlights
Robust Demand Driven by a Big 12 University
With more than 25,000 students enrolled, the University of Kansas' Lawrence campus is the primary demand generator for the market. As a leading public research university, KU attracts a steady flow of faculty, performers, visiting families, and event attendees. Its status as a Big 12 program also fuels strong demand around home athletic events. Allen Fieldhouse ranks among the nation's most storied college basketball venues, and the Jayhawks have sold out nearly 400 consecutive men's basketball games dating back to 2001. KU football adds further demand to Lawrence on game weekends at David Booth Kansas Memorial Stadium, which recently completed phase one of a $450 million renovation.
Continued RevPAR Growth
The Hotel has delivered strong RevPAR gains over the past year, with TTM RevPAR through May 2026 up 9.1% year-over-year — pushing RevPAR penetration to nearly 120%, largely on the strength of occupancy improvement. Further occupancy growth for a new owner can likely be attained, supported by significant growth in corporate demand in the market, as well as KU's continued growth in enrollment and athletic offerings. This should also position a new owner to capture additional rate upside, particularly given the market's limited new supply pipeline. Together, these dynamics position a new owner to acquire an asset with clear, demonstrated cash flow momentum.
Increased Corporate Demand
The University of Kansas has completely changed the corporate landscape in Lawrence, with biosciences and manufacturing becoming more prominent than ever before. Since 2010, more than 30 companies have added offices in or near Lawrence to focus on their partnership with KU, and many of these companies have established offices in the KU Innovation Park or the Lawrence VenturePark.
Limited New Supply
The only hotel currently in Lawrence's development pipeline is a 164-key Tribute Portfolio property planned adjacent to the football stadium (per CoStar), located approximately 3.8 miles from the Holiday Inn Express. Given its positioning as an upper upscale, soft-branded asset, the Tribute Portfolio property is unlikely to compete directly with the subject property and should instead help to lift the market's ADR ceiling, serving as a benefit to the Holiday Inn Express.
Brand Flexibility
The current franchise agreement expires February 1, 2027 and will not be renewed, understood to be driven by IHG’s development pipeline in the market rather than any issue with the existing asset itself. The Property will be sold unencumbered by brand, giving a buyer maximum flexibility. Several brands have already expressed interest in a potential conversion, including City Express by Marriott (~$30K/key PIP estimate) and Best Western Plus (~$15K/key PIP estimate).
Excellent Opportunity for Owner/Operator
This well-maintained asset offers an attractive opportunity to acquire an absentee-owned hotel that is unencumbered by management. Given the asset’s strong cash flow, a new owner/operator is well-positioned for success in a Big 12 market.

Photo Gallery