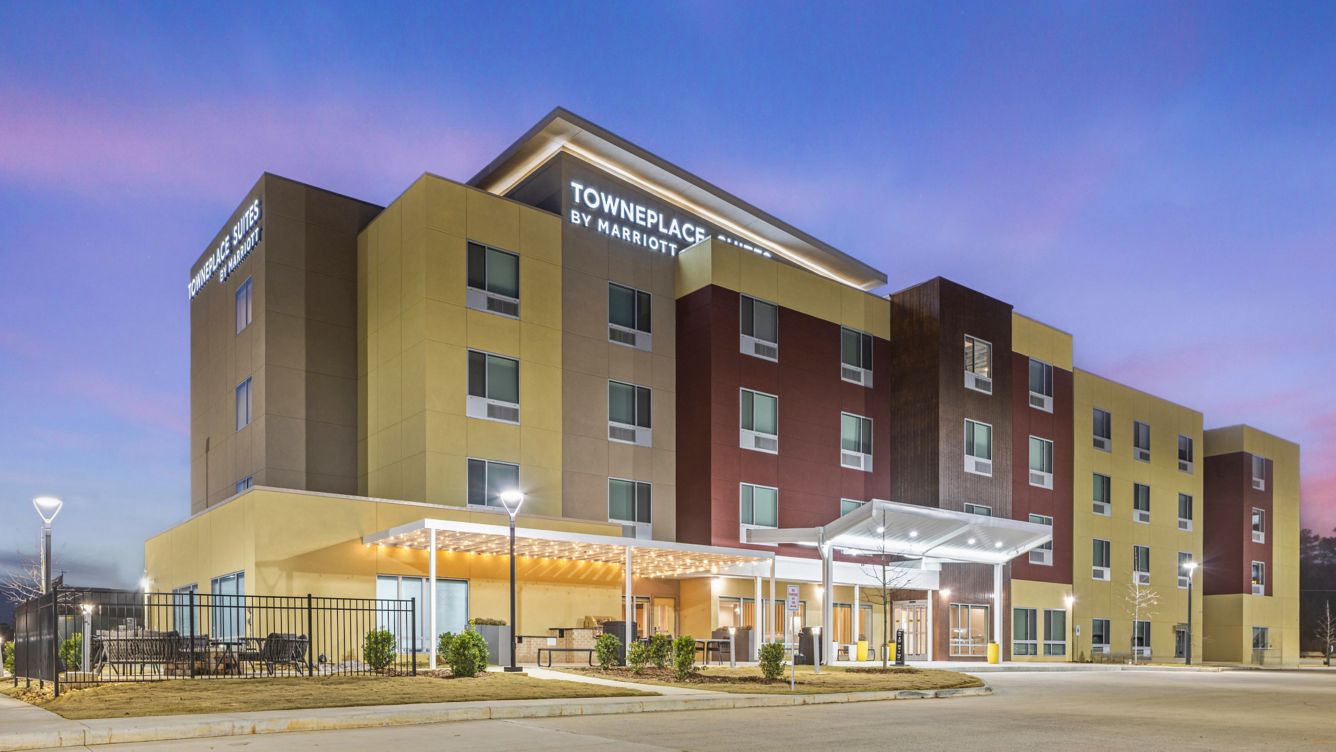
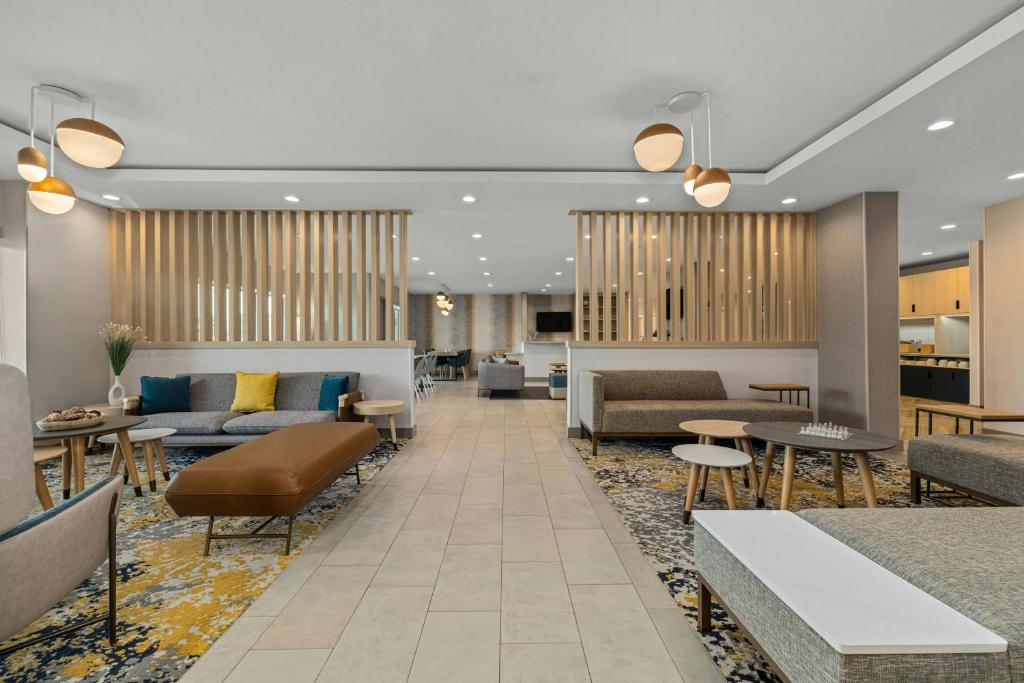
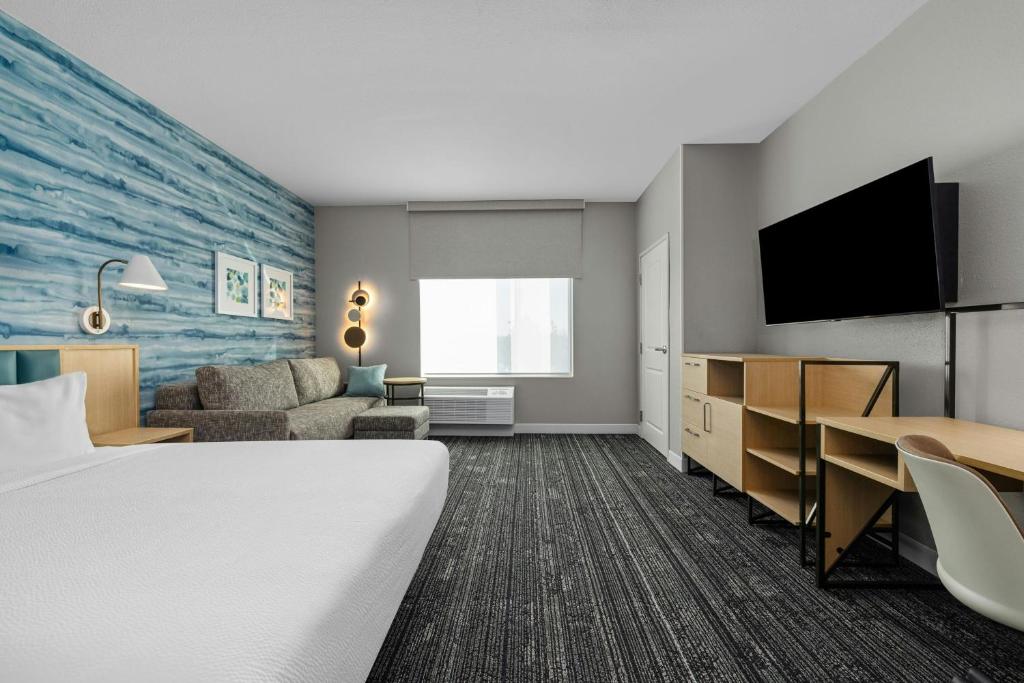
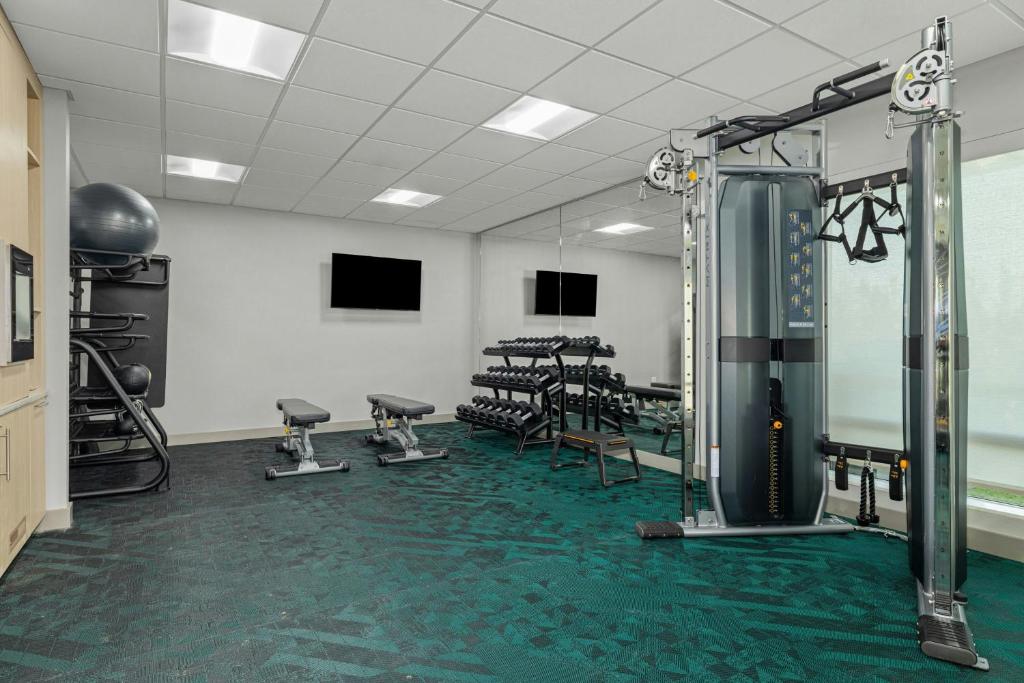
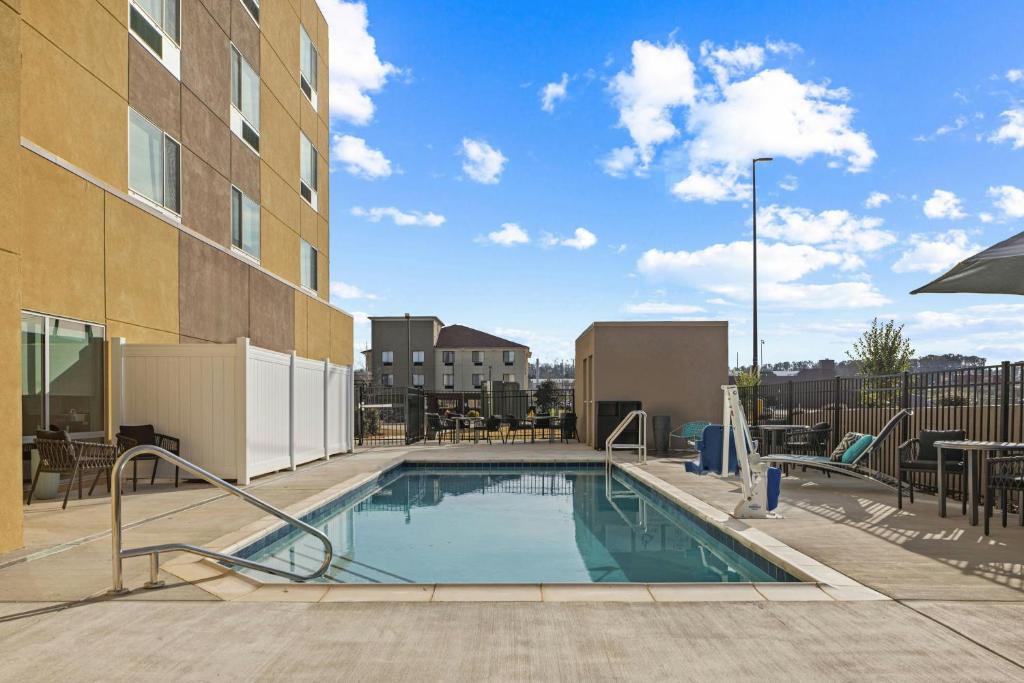
Hunter Advisors has been exclusively engaged to solicit offers for the acquisition of the TownePlace Suites by Marriott Pell City (the "Hotel" or "Property"), an 89-suite, newly constructed extended-stay asset strategically positioned directly off Interstate 20 in Pell City. Construction was completed in October 2025, providing a buyer with a turnkey, institutional-quality asset with no property improvement plan required at acquisition, eliminating the capital exposure, operational disruption, and timeline risk typically associated with a change-of-ownership transaction. The Property benefits from a diversified, multi-segment demand base, anchored by a deep concentration of manufacturing and industrial employers that generate steady corporate transient and project-based extended-stay demand well suited to the Property's all-suite, kitchen-equipped guestroom product. Most notably, Honda Manufacturing of Alabama, located a short drive from the Hotel, is moving forward with a $470 million expansion of its Lincoln operations, which is expected to drive incremental contractor, vendor, and workforce-relocation demand throughout the development period and beyond. This industrial demand base is complemented by significant leisure, sports, and healthcare-driven visitation, with Talladega Superspeedway, Logan Martin Lake, and the Pell City Sports Complex driving periodic tourism and event-related demand, and UAB St. Vincent's St. Clair and the Robert Howard Veteran Home, both approximately five minutes from the Property, contributing steady, non-seasonal medical-related transient business.
In less than a year of operation, the Hotel has achieved a strong ramp-up, already reaching 97.5% ADR penetration and 90.8% occupancy penetration against an established competitive set. It's also operating with a highly efficient cost structure that compares favorably to stabilized extended-stay assets of similar scale. With penetration still below fair share, the Hotel has a clear path to further top-line growth as its rate and occupancy positioning catch up to its newly built product quality and brand standing. This upside is protected on the supply side, as no new hotel supply is currently under construction within five miles of the Property, allowing an incoming owner to pursue RevPAR and market share gains without near-term competitive dilution. The combination of new construction with no PIP obligation, an already-efficient cost structure, a diversified demand base, and a continued ramp in a supply-constrained market presents investors with a rare opportunity to acquire a low-capital-risk extended-stay asset with a clear path to continued performance improvement.